 Hidden AI Risk: What Every Tech Company Should Know About Liability and Coverage
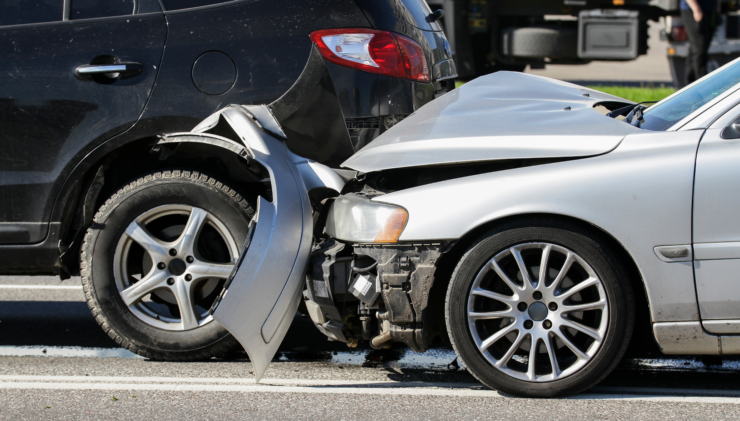
Both commercial auto insurance and personal auto insurance rates rose sharply in recent years, and while there are signs of relief, understanding why matters for anyone managing a vehicle or a fleet. Insurance rate trends are largely driven by claims trends, and recent auto claims trends have been characterized by growing risks and rising costs — with some recent signs of stabilization.
Key Takeaways
- Auto claims frequency and severity both rose sharply after the pandemic, with material damage severity up 47% and total loss claims up 29%, according to LexisNexis.
- Reckless and distracted driving increased during the pandemic and, according to recent survey data, many people believe dangerous driving habits have stuck around since.
- Vehicle repairs have gotten both slower and more expensive, driven by labor shortages, supply chain issues, and increasingly sophisticated (and costly-to-repair) vehicle technology.
- Repair cycle times have actually improved in the most recent data — down to 19.3 days in 2025, from 22.3 days the year before — though total losses now make up a growing share of claims (27%, up from 24%).
- Social inflation and large jury verdicts (“nuclear verdicts”) have added billions of dollars to auto insurance claims costs, affecting both commercial and personal auto lines.
- After peaking around April 2024, auto insurance rates have been gradually declining, though many customers have not yet felt the full effect of those decreases.
Claims Severity and Frequency Have Surged
LexisNexis reports that auto claims have increased in terms of both frequency and severity since the COVID-19 pandemic. Bodily injury severity is up by 20% and material damage severity is up by 47%, while total loss claims have increased by 29%.
It’s impossible to point to a single reason for the surge. However, multiple factors appear to be contributing to the problem, including reckless driving, repair costs, and litigation.
Reckless Driving Is Up
Blame it on stress; boredom; or the temptation of nearly empty roads. Regardless of the reason, reckless driving surged during the COVID-19 pandemic. We are still feeling the impact today.
A study by IIHS on Virginia drivers found that speeding by at least 10 mph increased by more than 50% between March and June 2020. This could explain why traffic fatalities increased by 7% in 2020 even though the number of miles driven plummeted. NHTSA data shows that the biggest increases in fatal crashes involved speeding or alcohol and unbelted vehicle occupants.
The pandemic has ended, but many people think reckless driving habits have become more common. In a survey from Pew Research Center, 49% of respondents said people are driving more dangerously than they did before the pandemic, compared to only 9% of respondents who said they’re driving more safely.
Distracted driving is also a problem, especially among young drivers. According to LexisNexis, distracted driving violations among Gen Z drivers have increased by 24% compared to 2022 and by 66% compared to 2019. However, this is not just a Gen Z problem – across all ages, distracted driving increased by 10% from 2022 to 2023.
Repairs Are Slower and More Expensive
Another pandemic-related change has contributed to higher auto claims: repairs have taken longer and cost more, though there’s been meaningful improvement recently. Faced with labor shortages and supply chain disruption during the pandemic, many auto repair shops developed long backlogs. The J.D. Power 2023 U.S. Auto Claims Satisfaction Study found that auto insurance repair times nearly doubled between 2021 and 2023. By the 2025 study, J.D. Power reports the average repair cycle time had improved to 19.3 days, down from 22.3 days the year before. That’s real progress, though still longer than typical pre-pandemic repair times.
Longer repair times may lead to larger claims costs. The longer the claim drags on, the greater the administrative costs. Insurers may also incur additional costs due to rental coverage.
On top of these challenges, auto insurance claims costs are rising due to the changing nature of vehicles. As vehicles adopt more sophisticated technology, repairs become more costly. A car bumper loaded with sensors and cameras may help you avoid a crash, but, if you crash, that bumper will be expensive to repair. Even minor crashes may necessitate costly repairs and realignments. In fact, J.D. Power’s 2025 data shows that vehicles with three or more advanced driver-assistance features now average 21.5 days in the shop, compared to 17.9 days for older vehicles without that technology.
The rise of electric vehicles is also a factor. According to Kelley Blue Book, electric vehicles cost 30% more to repair than gas-powered vehicles.
Litigation Is Adding to the Problem
Social inflation and nuclear verdicts have been leading to huge jury verdicts against transportation companies. Research from the Insurance Information Institute found that the inflationary total of $21 billion in auto insurance claims between 2014 and 2019 is due to social inflation. Some jury awards – such as a $141.5 million nuclear verdict against a small Florida trucking company (as reported by FreightWaves) – are astounding.
However, social inflation isn’t just an issue for commercial auto insurance. In a study from the Insurance Research Council, 89% of people recalled seeing attorney advertising in the past year and 52% of people thought attorney advertising increased the cost of insurance.
Is There Any Relief in Sight?
There are some early signs of stabilization. After peaking around April 2024, auto insurance rates have been gradually declining, and repair cycle times have continued to improve — the 2025 J.D. Power study puts the average at 19.3 days, down from 22.3 days the year before. However, many customers haven’t yet felt the benefit of falling rates, and a growing share of claims — now 27%, up from just 16% in 2022 — are resulting in total losses rather than repairs, which keeps overall claims costs elevated even as individual repair times improve.
What Should Drivers Do?
The increase in claims costs is hard on insurers, but the resulting increase in insurance rates is hard on drivers and business owners. However, there are steps that you can take:
- Embrace cameras. Businesses should use dashcams and in-cab cameras to promote safe driving and ensure drivers who are not at fault are exonerated after a crash. Individual drivers may also like to invest in dashcams – if someone tries to stage a crash, a dashcam may be the only proof you have.
- Consider telematics. Businesses should use telematics to identify risky driving habits and improve operational efficiency. Individual drivers may also benefit from telematics and usage-based insurance programs, especially if they’re safe, low-mileage drivers. In our experience, businesses that adopt telematics see the clearest ROI when they pair the data with an actual coaching program — collecting driving data without acting on it rarely moves the needle on claims.
- Drive safely. The most important thing to do to keep claims and costs down is to be a safe driver. Don’t speed, don’t drive under the influence, make sure everyone in the vehicle is using a seatbelt, and give the road your full attention. Encourage your family members and your colleagues to adopt safe driving habits.
Talk to Us Before Your Next Claim, Not After
Are you looking for personal or commercial auto insurance? Heffernan Insurance Brokers can help you find coverage that reflects today’s claims environment — reach out to talk through your options, whether you’re insuring a personal vehicle or a full commercial fleet.